AI Agent Adoption Journeys at Community Banks and Credit Unions
Governance built from day one, not retrofitted later, separates scaling programs from stalled ones.
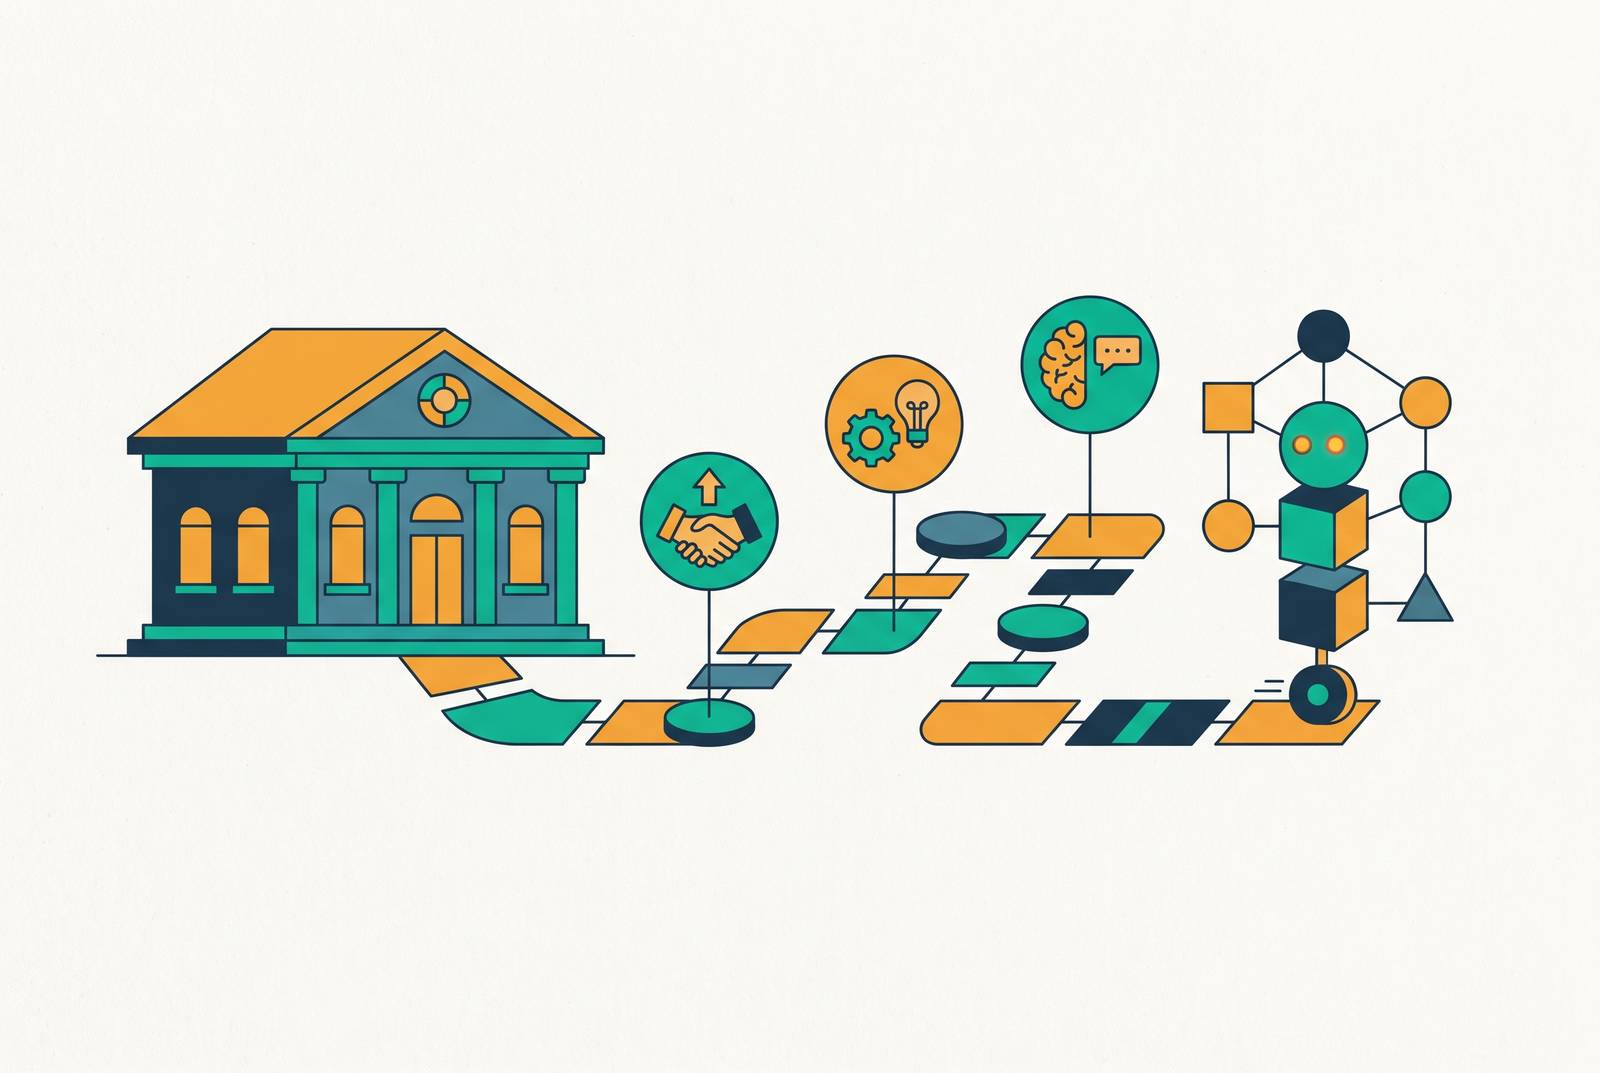
Community banks and credit unions adopting agentic AI move through four recognizable stages, from a contained pilot to full transaction execution. The ones that get it right treat governance and auditability as the foundation at every step, embedding them from the start rather than adding them once the pilot works. That single choice, more than any vendor picked or feature shipped, separates a program that scales from one that stalls out at stage two. Most of the industry still hasn't decided which side of that line it wants to be on.
2025 was the year banks spent picking use cases and drafting internal AI policy. Hunton Andrews Kurth's Top 10 Tech Issues for Regional and Community Banks calls 2026 the year those policies run into operational reality, as agentic AI spreads across both physical and digital commerce. CCG Catalyst points to the first week of May 2026 as the moment agentic AI stopped being theoretical, showing up instead as named institutions, funded infrastructure deals, and live systems. CB Insights tracked the money behind it: AI agent M&A hit close to a hundred deals in 2025, a tenfold jump year over year. This is not a side experiment anymore, and treating it like one is the first mistake.
Plenty of the sector hasn't started, though. Cornerstone Advisors' "What's Going On in Banking 2025" found 28% of banks and 29% of credit unions planned to roll out generative AI for the first time that year. A large chunk of the industry is still figuring out where to begin, and the gap between the movers and everyone else is only going to widen.
Old AI gave you a response. Agentic AI gives you a resolution. That's not a marketing line, it changes every stage that follows, because a system trusted to resolve something has to be trusted to act, not just to talk.
What the adoption curve looks like across institutions
Wolters Kluwer's Q1 2026 Banking Compliance AI Trend Report surveyed 148 financial institutions. About 31.8% already run AI or machine learning in production, and another 29.1% are actively piloting. Add those together and roughly 61% of institutions are somewhere on the active adoption curve. That sounds like momentum, until you look at what's actually holding it up.
Maturity is thin underneath that number. Only 12.2% of those same institutions call their AI strategy well-defined and properly resourced. So most of the sector is moving without a finished plan in hand. Atul Dubey, EVP at Wolters Kluwer, said banks are moving fast to embed agentic AI, "potentially at the expense of clear strategy and AI governance."" Speed and readiness aren't running at the same pace, and that gap is where the real risk sits. If one in eight institutions has an actual strategy, what are the other seven running on?
Using AI to summarize a document and letting an AI agent move money are not the same animal. That gap, between using AI and letting AI execute, is where most of the industry's real work still lives. What's been deployed so far tends to be foundational and unglamorous: AI voice replacing legacy IVR systems, chatbots handling web and mobile questions, AI folded into loan underwriting review. It's the base the later stages get built on, and skipping it doesn't speed anything up.
Three core providers serve more than 70% of depository institutions, so a community bank's AI roadmap often runs on its core provider's clock whether the bank likes it or not. The ABA's 2024 Core Platforms Survey rated overall satisfaction at just 3.19 out of 5. So adoption isn't uniform. Some institutions are boxed in by what the core allows. Others are moving faster by layering AI on top of the core instead of waiting for it to change, and that second group is setting the pace for everyone else.
Stage one, scoping the pilot around a contained, auditable use case
The first pilots tend to look alike: voice AI swapping out legacy IVR, a chatbot fielding FAQ and account-balance questions, AI-assisted review sitting inside loan underwriting. All three share the same trait. They're bounded, reversible, and easy to measure. That's the whole point of a pilot, and any pilot missing one of those three things isn't really a pilot.
A pilot's real value is what it teaches about failure, not just what it automates. Keep the scope narrow and a mistake gets caught before it touches a member at scale. Widen it too soon, and the same mistake gets caught by an examiner instead.
Legacy IVR makes a natural entry point because the gap is so wide. Traditional IVR systems typically resolve only 20 to 30% of inquiries without routing to a human. Voice AI can resolve a substantially higher share of inquiries without human routing. That gap produces a clear signal fast, which matters when a credit union's board wants results in a quarter, not a year. Some credit unions have gone live in as little as two weeks with no major IT build required. There's no reason to over-engineer the pilot itself.
What belongs in the pilot from day one is what makes its results trustworthy: defined escalation paths so a stuck conversation lands with a human, and a complete log of every action the system took. Skip either one and the pilot produces a demo instead of data. Platforms built with this in mind let a pilot generate believable data from week one instead of retrofitting governance after the fact.
For institutions boxed in by their core, there's a practical shortcut: pilot the AI above the core, on existing rails, instead of trying to replace infrastructure. That sidesteps a multi-year integration fight while still producing real operational data.
Stage two, reading pilot results honestly and deciding what to expand
The metrics that matter here are containment rate, escalation rate, error type, member satisfaction, and one that gets skipped too often: whether the audit trail the pilot produced is complete enough to hand an examiner without flinching. Skip that last one and everything else is just decoration.
Great Lakes Credit Union hit an 80% call containment rate after moving to voice AI. WEOKIE Federal Credit Union reported saving $800,000 a year after cutting outsourced support. Those numbers show what a well-structured pilot produces when it works, though copying the tech doesn't guarantee copying the result.
Pilots reveal what an RFP never will: how the system handles edge cases nobody anticipated, how staff actually behave when the AI hands them something to review, and whether automation bias is creeping in, meaning employees start rubber-stamping AI output instead of checking it. That last one deserves its own pause. Automation bias is a human problem, not a technical one, and no amount of staff training fully solves it. Governance has to catch the deference before it becomes a habit, built into the system itself rather than corrected after the fact.
So at this stage the honest task is deciding which functions are genuinely ready to expand, and which need tighter controls before they touch payments, lending decisions, or anything that commits the institution to a member. The Wolters Kluwer US Banking AI Risk and Governance Index found lending and underwriting (33%) and collections and recovery (30%) are the functions where agentic AI carries the most risk without solid human-in-the-loop controls. Those aren't the functions to expand on momentum alone, no matter how good the containment rate looked in week one.
Stage three, building the governance infrastructure that makes scaling safe
Most credit unions and community banks already have AI agents running somewhere in the business. Fewer than 1 in 8 have a governance program built to match, according to industry research. That gap should give anyone pause. McKinsey's survey found something similar at a broader scale: only about a third of organizations report mature governance. The AI is already live almost everywhere. The people watching it, mostly, aren't ready for what happens when it fails.
The sharpest version of this question is whether an institution can actually shut an AI model off when something goes wrong. In the same Wolters Kluwer Index, 72% of respondents couldn't say with confidence that their institution had an effective kill switch for AI models, or a reliable process for reporting model failures to supervisors. Broken down further, 34% cited a lack of formal kill-switch protocols and 38% cited weak regulatory reporting mechanisms. These are concrete gaps, not abstract ones, and they're the exact items an examiner asks about directly. Model governance and validation ranked as a primary barrier to scaling AI in that Index. Governance, not the technology, is the bottleneck. The tech mostly works. The oversight around it mostly doesn't yet.
Backbase, in a 2026 framework, lays out four pillars that hold up under scrutiny:
- Accountability: someone at the executive level owns every AI outcome, by name
- Transparency: the institution can explain how a model reached a specific decision, not just that it did
- Auditability: every automated action leaves an immutable record regulators can pull
- Model validation: ongoing testing, not a one-time check at launch
On the regulatory side, institutions are being pushed to align with the NIST AI Risk Management Framework and ISO/IEC 23894, while watching the EU AI Act's Annex III high-risk deadline, now set for December 2027 after the original August 2026 date got pushed back under the Digital Omnibus (Regulation EU 2026/1744, in force since July 27, 2026). The BIS Committee on Global Risk Management flagged this in a January 2025 report, warning that without robust AI governance, operational, reputational, and model risks can accumulate until they don't.
Credit unions have a specific signal here. Reports indicate the NCUA established a comprehensive AI Compliance Plan and hired three AI officers for 2025 and 2026, a regulator clearly paying attention. That's a regulator paying attention, and it cuts both ways. Institutions doing this responsibly aren't operating in a vacuum, and institutions cutting corners won't be able to claim nobody was watching.
What governance infrastructure actually looks like in practice: versioned policies that can be rolled back if something breaks, compliance controls ops teams can tune without filing an engineering request, automated QA that flags a missing disclosure before it goes out the door, and a complete audit trail behind every single AI-initiated action.
Stage four, moving AI agents from service interactions into transaction execution
An AI agent that answers "what's my balance" and one that moves money sit on entirely different risk planes. That's the line this stage crosses, and it marks a genuine threshold, not just the next feature release.
Industry analysis distinguishes two layers of agentic activity: one where agents act autonomously inside narrow, defined parameters, and one where agents manage entire purchasing workflows end to end. Community banks, right now, are stepping into the first layer, not the second, and confusing the two is how a pilot turns into a headline.
Capgemini's World Payments Report expects non-cash transaction volumes to climb from 1,685 billion in 2024 to 3,540 billion by 2029. Whatever share of that runs through agent-initiated transactions grows right alongside it.
Collections is emerging as the early production proving ground for transaction-executing AI. Credit unions reported total delinquency at 95 basis points in the third quarter of 2025, and 30-to-59-day delinquencies climbed to 1.13% by September 2025, edging back toward pre-pandemic levels. Early-stage delinquency outreach is high-value work, and it's exactly the kind of work that goes bad fast without tight controls, whether that means a wrong disclosure, a missed quiet-hours rule, or a compliance gap on a recorded call.
That's the environment purpose-built collections products are stepping into: a policy engine that checks every outreach attempt against cadence rules, quiet hours, permissions, and institution-specific overlays before it happens, plus automated QA that catches missing disclosures or disallowed language, plus native integration with core providers so nothing requires a separate system of record.
Backbase's AI-native Banking OS, launched in April 2026, takes a similar approach with what it calls a Sentinel layer, checking every action against bank policy before execution and logging it afterward. The pattern across the leading platforms holds steady: permission-checking and logging get built into the execution path itself from the outset.
Salient's production numbers show what durable deployment looks like when this is done right. Running end-to-end loan servicing workflows in production, the company reported a 100% pilot-to-contract conversion rate, against an industry AI fintech churn range that runs 22 to 76%. That's the gap between a demo that impresses and a system institutions actually keep running.
For mid-tier banks weighing whether any of this is even reachable, the reassurance is structural: AI can plug into existing payment infrastructure without a full core replacement. PaymanAI, for instance, deploys AI agents that execute real bank transactions on a financial institution's existing rails. Deploying on existing rails is what makes transaction-level AI a near-term project instead of a multi-year overhaul.
What the vendor landscape offers institutions at each stage
The vendor field splits roughly by where an institution sits on the adoption curve.
Eltropy runs a unified communications platform serving 750 financial institutions, adding more than 100 new clients in 2025. It acquired the collections technology firm Lexop in January 2025 and, in March 2026, launched what it describes as the industry's first agentic AI platform built specifically for credit unions, aimed at member servicing and self-serve payment workflows.
Backbase's AI-native Banking OS, launched April 2026, adds three layers on top of its existing platform: Intelligence for signal detection, Nexus as a shared semantic record, and Sentinel as the permission-checking authority layer with full action logging. Backbase also acquired the agentic AI firm Kasisto and now serves more than 120 financial institutions, with 2025 revenue above $350 million and named clients including Navy Federal Credit Union, TD Bank, and KeyBank.
Q2 launched Q2 Assistant in June 2026, a unified AI layer embedded across its product portfolio, connecting a conversational interface to product-specific agents built to execute tasks, not just answer questions.
Temenos announced AI Agents, Copilots, and a Conversational Studio in May 2026, embedded across its Core, Digital, and Financial Crime Mitigation products. A Microsoft integration brings governed Azure AI agents directly into Temenos core banking for multi-step AML and lending workflows, with auditability and human-in-the-loop design built in from the start.
Whatever the vendor, the same questions apply at every stage. Does the platform run on existing infrastructure, or does it demand a core replacement first? Can ops teams adjust controls themselves, without waiting on an engineering queue? Does every agent action generate a record that can't be edited after the fact? Is it SOC 2 certified or equivalent, and does it escalate to a human by design? An institution that can't answer all four isn't ready to move past stage one, no matter what the vendor's deck promises.
How governance posture at each stage shapes what examiners expect
There's no settled federal AI rulebook to lean on. California, Colorado, Texas, and Illinois are each pursuing their own state-level AI laws, and a December 2025 executive order pushed toward what it called a "minimally burdensome national policy framework for AI." Institutions need governance built to adapt to ground that's still shifting under them, keeping pace with rules as they change instead of fixing what's already broken.
What examiners are starting to ask isn't abstract. Can the institution produce an audit trail for AI-initiated actions on demand? Is there a documented kill-switch protocol? How is the model validated on an ongoing basis after launch, rather than just at the point it went live?
That 38% figure from the Wolters Kluwer Index, institutions citing weak regulatory reporting mechanisms as a governance gap, points directly at what happens next. It's the exact place where a routine exam turns into a finding, a real weak spot rather than a hypothetical one. And it's where stage-three governance and a bolted-on compliance memo look obviously different to the person sitting across the table asking questions.